Commercial Equipment Lending for Startup Motor Carriers: Understanding Underwriting Benchmarks
For an entrepreneur launching an independent motor carrier operation, financing your first Class 8 commercial tractor is typically the largest capital hurdle you will encounter. Commercial vehicle financing is fundamentally distinct from personal automotive loans: lenders evaluate the loan not merely on personal credit, but on commercial cash flow predictability, equipment depreciation velocity, and commercial driver experience.
Traditional commercial banks and captive OEM lenders view motor carrier authorities with less than two years in business as "high-risk startup credits." Statistically, over 30% of new motor carriers fail or surrender their operating authority within their first twelve months due to cash flow shortfalls or unexpected mechanical breakdowns.
To mitigate this risk, commercial equipment lenders enforce specialized underwriting parameters for new authorities, requiring larger down payments, rigorous verification of commercial CDL driving experience, and substantial liquid cash reserves.
- The "Time in Business" (TIB) Hurdle: Traditional prime commercial lenders require a minimum of 2 years of established motor carrier authority. New authorities must work with specialized "startup-friendly" commercial equipment lenders.
- Commercial CDL Experience Requirement: Most commercial underwriters mandate that the borrower or primary guarantor hold a valid Class A CDL for at least 3 to 5 continuous years, demonstrating mechanical familiarity and industry longevity.
- Down Payment Benchmarks (10% to 30%): While established fleets finance equipment with 0% to 5% down, startup carriers typically must provide 15% to 25% down in cash to offset initial depreciation.
- Vehicle Age & Mileage Caps: Lenders restrict financing on used commercial tractors to vehicles under 7 to 10 years old with fewer than 600,000 to 700,000 engine miles, ensuring the equipment maintains collateral resale value.
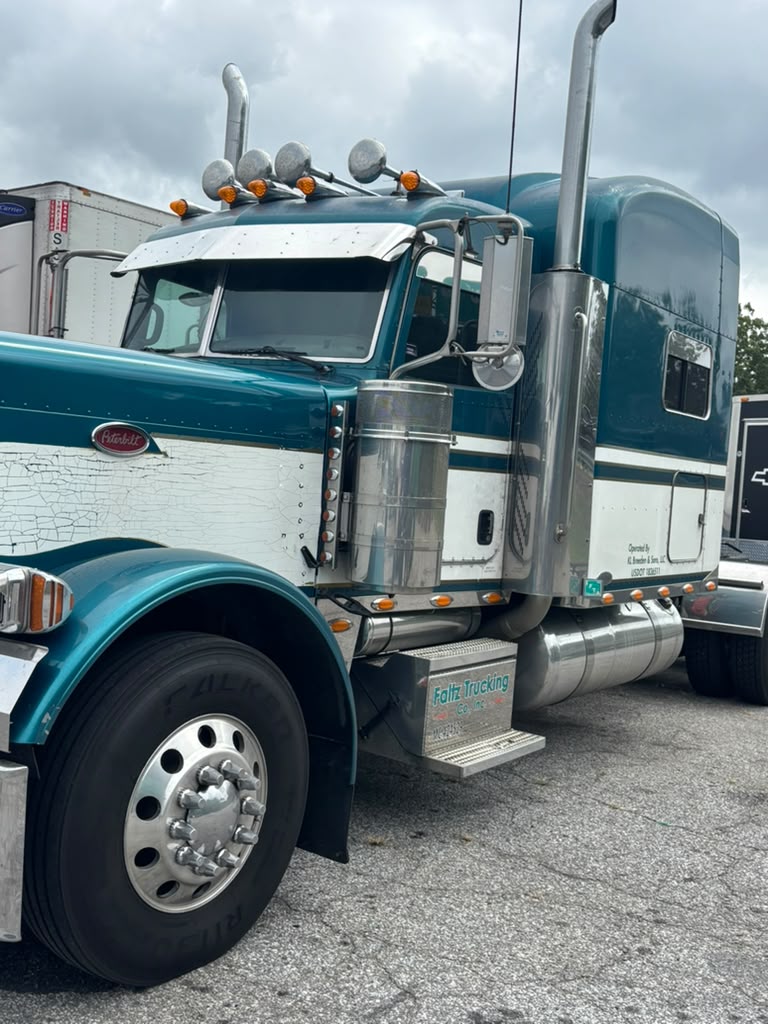
Figure 7.2: Commercial equipment lenders evaluate tractor age, engine overhaul records, and borrower CDL driving experience when approving equipment financing for new authorities.
Ensure Commercial Authority Compliance with Form HVUT 2290
Once your commercial truck financing is approved, protect your title and registration. E-file Form HVUT 2290 with Consulics and secure your stamped Schedule 1 in minutes.
e-File Form HVUT 2290 Now →Credit Tier Benchmarks, Interest Rates, and Building a Bulletproof Application Package
Securing competitive commercial interest rates requires presenting a comprehensive commercial loan package that answers every underwriter concern before they ask:
- Tier 1 Credit (700+ FICO, Homeowner, 5+ Yrs CDL): Qualifies for 8% to 12% interest rates, 10% to 15% down payment, and 48-to-60-month loan amortization terms.
- Tier 2 Credit (640–699 FICO, 3+ Yrs CDL): Interest rates range from 12% to 18%, requiring 20% down payment and 36-to-48-month loan terms.
- Tier 3 / Subprime Credit (<640 FICO or Past Derogatories): Interest rates climb to 19% to 28%, requiring 25% to 35% cash down payment and potential collateral liens on secondary assets.
- Mandatory Operating Capital Reserves: Never spend 100% of your available liquidity on the equipment down payment. Underwriters demand proof of at least $10,000 to $20,000 in liquid post-closing cash reserves to absorb fuel, insurance deposits, and initial maintenance.
- Title Registration & Form 2290: Once purchased, state DMVs require immediate proof of IRS Form 2290 Stamped Schedule 1 to issue apportioned IRP license plates for any commercial motor vehicle with a taxable gross weight of 55,000 pounds or more.
| Underwriting Tier | Borrower Profile & FICO | Typical Down Payment | Estimated APR & Terms | Equipment Age Restrictions |
|---|---|---|---|---|
| Tier 1 (Prime Startup) | 700+ FICO, 5+ yrs CDL, strong cash reserves | 10% – 15% down | 8.5% – 12.0% (48–60 mos) | Under 7 years old (<550k miles) |
| Tier 2 (Standard Startup) | 640 – 699 FICO, 3+ yrs CDL, modest reserves | 15% – 25% down | 12.5% – 18.0% (36–48 mos) | Under 10 years old (<650k miles) |
| Tier 3 (Credit-Challenged) | 580 – 639 FICO, limited time CDL, prior collections | 25% – 35% down | 18.5% – 26.0% (24–36 mos) | Under 12 years old (<750k miles) |
| Lease-to-Own / Asset-Based | <580 FICO or prior bankruptcy, proof of contracts | 30% – 40% down | 24.0% – 32.0% (24–36 mos) | Under 15 years old with engine dyno |
Filing HVUT 2290 for Your CDL Commercial Vehicle?
Consulics provides the fastest, most reliable IRS-authorized Form 2290 e-filing for motor carriers. Receive your official stamped Schedule 1 in minutes.
e-File Form HVUT 2290 Online →Related resources
- File Form 2290 online
- How to file Form 2290, step by step
- HVUT and the stamped Schedule 1, explained
- Estimate your tax with the HVUT 2290 calculator
- Check your Form 2290 due date
- Carrier Lease-Purchase vs Company Driver Guide
- Freight Factoring Cash Flow Guide for Truckers
- Commercial Truck Fuel Cards & Discount Programs Guide
- DOT New Entrant Safety Audit Preparation Guide
- E-File IRS Form 2290 Online
- IRS Stamped Schedule 1 Proof of Payment
- Form 2290 Due Date & Penalty Calculator
- FMCSA CSA Scores & SMS BASICs Optimization Guide
More Form 2290 and HVUT guides
- Carrier Lease-Purchase vs Company Driver Guide: Contract Pitfalls, Balloon Payments, and Truth in Leasing
- DOT, OSHA & ANSI Truck Emergency Safety Kit & Tools Guide: FMCSA Compliance Requirements
- Commercial Truck Winter Driving & Tire Chaining Laws Guide: State-by-State Regulations, Chain Types, and Fuel Anti-Gel
- Spot Market vs Contract Freight Guide: Rate Calculations, Load Board Bidding, and Lane Density
- Buying vs. Leasing a Semi-Truck: Complete Tax, Financing, and Form 2290 Responsibility Guide
- How to Slide Tandems and Balance Commercial Truck Axle Weights: Federal Bridge Formula, Kingpin Rules, and CAT Scale Guide
Ready to file your Form 2290?
IRS-authorized e-filing — get your stamped Schedule 1 in minutes.
e-File Form 2290 Now →This post is general information for motor carriers, not tax or legal advice, and government rules, systems, and fees can change at any time. Confirm anything before you rely on it with the IRS, the FMCSA, or a qualified professional. Consulics does not guarantee its accuracy or currency and accepts no liability for information an agency later changes.